Confidence Is Not a Strategy: The Hidden Cost of Oversizing Your Best Ideas
There is a particular kind of investor—ambitious, research-driven, and deeply self-assured—who builds a portfolio that looks less like a diversified blueprint and more like a concentrated bet. They have done the work. They have read the earnings transcripts, stress-tested the balance sheet, and tracked the management team for years. So when the opportunity arrives, they go big.
And sometimes, they are right. But the times they are wrong can erase years of progress in a matter of weeks.
This is the paradox at the heart of position sizing: the trades you are most confident about are frequently the ones that carry the most hidden risk. Understanding why requires both a mathematical framework and an honest examination of how the human brain processes certainty.
The Mechanics of Conviction Bias
Behavioral economists have long documented a phenomenon known as overconfidence bias—the tendency for individuals to overestimate the accuracy of their own predictions. In a general context, this might lead someone to underestimate how long a home renovation will take. In investing, it leads them to allocate 25 percent of their portfolio to a single position.
The cognitive process works like this: the more time and effort an investor invests in researching a particular stock, the more ownership they feel over the thesis. Psychologists call this the IKEA effect—we assign disproportionate value to things we have built ourselves. A stock idea that took three months to develop feels more reliable than one that took three days, even if the underlying evidence is equally uncertain.
This emotional attachment distorts risk perception. The investor is no longer evaluating the position objectively; they are defending a conclusion they have already reached.
What the Math Actually Says
Professional portfolio managers often rely on a framework known as the Kelly Criterion to determine optimal position sizing. Developed by mathematician John L. Kelly Jr. in the 1950s, the formula calculates the ideal fraction of capital to allocate to a trade based on the probability of winning and the ratio of potential gain to potential loss.
The formula itself is straightforward: f = (bp - q) / b, where b is the net odds received, p is the probability of winning, and q is the probability of losing.
What is striking about the Kelly Criterion—and what most individual investors never internalize—is that even under highly favorable conditions, the formula rarely justifies concentrating more than 10 to 15 percent of a portfolio in a single position. Yet retail investors routinely exceed this threshold when they feel strongly about an idea.
Furthermore, the Kelly Criterion assumes you know your edge with precision. In practice, that edge is almost always uncertain. Many professional traders deliberately use a fraction of the Kelly output—sometimes half or even a quarter—precisely because real-world probabilities are never as clean as they appear on a spreadsheet.
Case Study: The Tech Concentration Trap
Consider a composite scenario that mirrors patterns seen repeatedly during the 2020–2022 market cycle. An individual investor, emboldened by strong returns in the technology sector, gradually increased their allocation to a single cloud-software company from 8 percent to nearly 40 percent of their total portfolio. Their rationale was sound: the company had superior revenue growth, a sticky customer base, and a dominant position in its niche.
When interest rates began rising in 2022 and growth-stock valuations compressed sharply, that single position fell more than 60 percent from its peak. The investor's overall portfolio declined by roughly 28 percent—nearly three times the loss they would have experienced had they maintained an 8 percent allocation.
The thesis was not wrong in any fundamental sense. The company survived, adapted, and eventually recovered. But the position size transformed a manageable drawdown into a psychologically devastating loss that prompted panic selling near the bottom.
This is the cruelty of oversizing: it converts a correct long-term thesis into a short-term catastrophe by making the volatility unbearable.
How Professional Traders Think About Sizing
Institutional portfolio managers approach position sizing as a primary risk management tool, not an afterthought. Several principles guide their methodology.
Risk-based allocation. Rather than deciding how much they want to own of a company, professional traders first determine how much they are willing to lose. A common rule is to limit any single position's potential loss to one to two percent of total portfolio value. From there, position size is calculated backward based on the distance to a defined stop-loss level.
Correlation awareness. Two positions in different companies can behave like a single concentrated bet if both are highly sensitive to the same macroeconomic variable—say, interest rate movements or semiconductor supply chains. Professionals account for this correlation when aggregating risk across a portfolio.
Scaling in, not diving in. Rather than deploying full capital at the outset, experienced traders frequently build positions in tranches. This approach reduces the emotional pressure of a single entry point and allows new information to influence sizing decisions before full exposure is established.
The Emotional Architecture of a Losing Trade
When a large position moves against an investor, a predictable psychological sequence unfolds. First comes denial—the conviction that the market is wrong and the thesis remains intact. This phase can last weeks or months, during which the investor often adds to the position rather than trimming it, a behavior known as averaging down.
Next comes rationalization, where the investor reframes the loss as temporary or cyclical. This is frequently accompanied by a reluctance to discuss the position with others, which eliminates the external feedback that might prompt a more rational reassessment.
Finally, if the position continues to deteriorate, capitulation arrives—often at the worst possible moment, when fear overwhelms logic and the investor sells at or near the bottom.
Each stage of this sequence is made more severe by the size of the position. A 5 percent allocation that falls 50 percent is a 2.5 percent portfolio loss—uncomfortable but survivable. A 30 percent allocation that falls 50 percent is a 15 percent portfolio loss—the kind of damage that can set a long-term wealth-building plan back by years.
Building a Position Sizing Framework
For investors who want to bring more discipline to this process, a few practical steps can help anchor decision-making before emotion enters the picture.
First, establish a maximum single-position limit before you begin building any portfolio. Many financial professionals recommend capping individual equity positions at 5 to 10 percent for most investors, with only exceptional circumstances justifying more.
Second, document your sizing rationale in writing at the time of purchase. Articulating why a given allocation is appropriate—rather than simply acting on conviction—forces a more deliberate thought process.
Third, review your largest positions on a regular schedule and ask a pointed question: Would I initiate this position at this size today, given what I now know? If the answer is no, that is a signal worth heeding.
The Blueprint Perspective
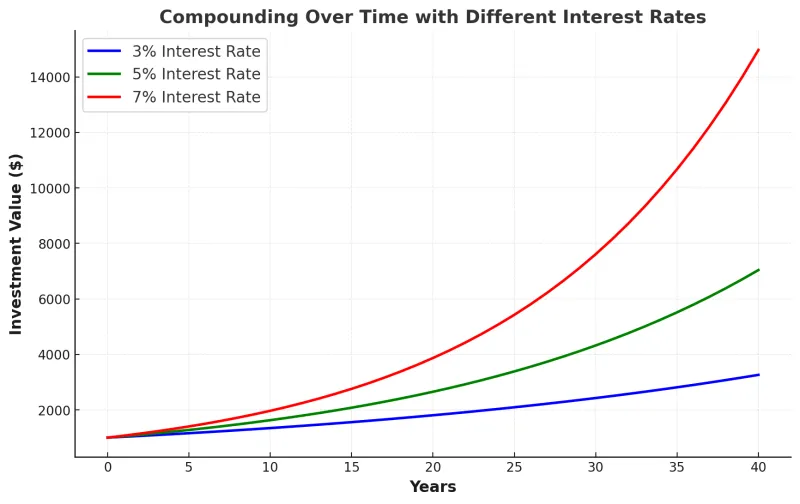
Building wealth through equity investing is a long-term endeavor, and the most durable portfolios are rarely the most aggressive ones. The investors who compound capital most effectively over decades are not necessarily those who identify the best ideas—they are those who manage risk skillfully enough to stay in the game long enough for their ideas to pay off.
Position sizing is not a concession to timidity. It is the structural discipline that keeps a single bad outcome from becoming a permanent setback. Confidence in your research is a valuable starting point. Letting that confidence dictate how much capital you risk is where the blueprint begins to crack.