When the Market Falls First: How Retirement Timing Can Make or Break Your Financial Legacy
Photo: John-Mark Kuznietsov mrrrk_smith, CC0, via Wikimedia Commons
Imagine two investors—call them David and Margaret—who each retire with $750,000, each averaging a 7% annual return over a 25-year retirement. By conventional math, their outcomes should look roughly identical. Yet one exhausts their portfolio before age 80 while the other leaves a meaningful estate to their heirs. The difference has nothing to do with discipline, savings habits, or even investment selection. It comes down to timing—specifically, the sequence in which their returns arrived.
This is the sequence of returns problem, and for investors approaching or already in retirement, it represents one of the most underappreciated threats to long-term financial independence.
What Sequence Risk Actually Means
Sequence of returns risk refers to the danger that the timing of poor investment performance—not merely its magnitude—will permanently impair a portfolio's longevity. During the accumulation phase of investing, this risk is largely irrelevant. A 30-year-old contributing regularly to a 401(k) who experiences a market downturn in year three actually benefits from buying more shares at lower prices. Time and continued contributions act as a natural buffer.
Retirement changes the equation entirely. Once an investor begins drawing down their portfolio to fund living expenses, the math inverts. Early losses force the retiree to sell a larger number of shares at depressed prices simply to meet withdrawal needs. Those shares are then unavailable to participate in any subsequent recovery. The portfolio's ability to generate future income is permanently reduced—even if the market eventually delivers strong returns in later years.
In short: a dollar lost in year one of retirement is far more damaging than a dollar lost in year fifteen.
The Historical Record Tells a Sobering Story
History offers instructive examples of how devastating early-retirement bear markets can be. Consider the cohort of Americans who retired in 2000, just as the dot-com bubble collapsed. The S&P 500 declined approximately 49% from its peak before recovering. Retirees who were withdrawing 4% or more annually during this period saw their portfolios erode at an accelerated pace. Many were forced to reduce withdrawals, return to work, or accept a substantially diminished standard of living—not because their long-term average returns were poor, but because the losses came first.
The 2008 financial crisis delivered a similar blow to those who had retired between 2006 and 2008. The S&P 500 lost roughly 57% from peak to trough. Retirees drawing down assets during that collapse experienced compounded damage: their portfolio values fell sharply while their withdrawal rates, measured as a percentage of the remaining balance, climbed steeply. Recovery, when it came, applied to a much smaller base.
Conversely, investors who retired in 1982—just as one of the longest bull markets in American history was beginning—enjoyed a dramatically different outcome, even if their average lifetime returns were comparable to the less fortunate cohorts above.
Why Average Returns Are a Misleading Benchmark
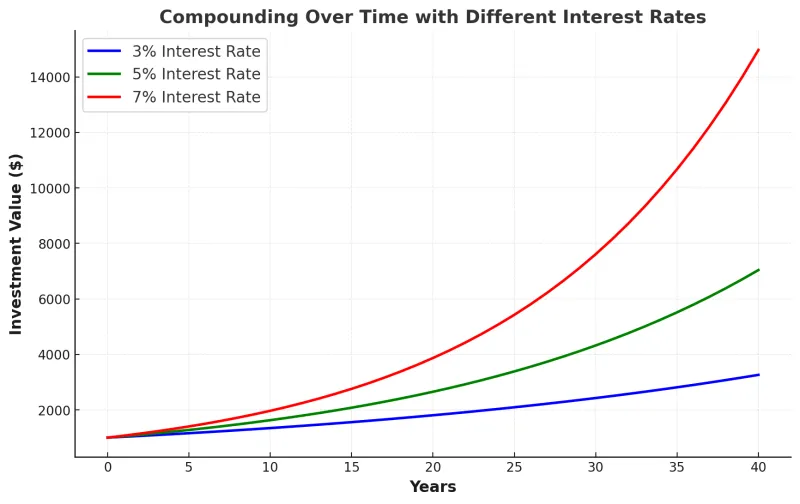
Financial projections frequently rely on average annual return assumptions. A plan might assume 7% annual growth, which sounds reasonable given long-term historical averages for a diversified equity portfolio. The problem is that averages obscure the variance that actually determines real-world outcomes.
Consider a simplified two-year example. Portfolio A earns +30% in year one and -10% in year two. Portfolio B earns -10% in year one and +30% in year two. The average annual return is identical. But if a retiree withdraws $40,000 at the start of each year, Portfolio B will have significantly less capital remaining after year two than Portfolio A—because the early loss forced liquidation at the worst possible moment.
This gap widens dramatically over a 20- or 30-year retirement horizon. Sequence risk does not just reduce wealth; it can eliminate it entirely.
Strategies to Mitigate the Sequence Risk Threat
The encouraging news is that sequence of returns risk is manageable with deliberate planning. Several proven strategies exist to protect retirement portfolios from this structural vulnerability.
Establish a Cash or Short-Term Bond Reserve
Maintaining one to three years of living expenses in cash equivalents or short-duration bonds allows retirees to meet withdrawal needs without selling equities during a downturn. This buffer gives the equity portion of the portfolio time to recover before it must be liquidated. It is one of the simplest and most effective defenses against sequence risk.
Adopt a Dynamic Withdrawal Strategy
Rather than withdrawing a fixed dollar amount each year, consider a flexible withdrawal approach that reduces distributions during periods of poor market performance. Guardrail strategies, for example, set upper and lower bounds on withdrawal rates and adjust spending accordingly. This approach requires some lifestyle flexibility but can significantly extend portfolio longevity.
Incorporate Non-Correlated Income Sources
Social Security, annuities, rental income, or pensions can serve as a reliable income floor that reduces dependence on portfolio withdrawals in any given year. When a guaranteed income stream covers basic living expenses, retirees can afford to leave their investment portfolio untouched during market downturns—allowing the compounding process to resume without interruption.
Revisit Asset Allocation at the Transition Point
The years immediately preceding and following retirement—sometimes called the "retirement red zone"—are the period of maximum sequence risk exposure. A modestly more conservative allocation during this window, gradually shifting back toward growth assets after the first five to seven years of retirement, can reduce the severity of early-retirement losses without sacrificing long-term growth potential.
Consider a Bond Tent Strategy
Some financial planners advocate temporarily overweighting bonds in the years surrounding the retirement date—building what is sometimes called a bond tent—before gradually reducing fixed-income exposure as the sequence risk window passes. This approach accepts lower expected returns in exchange for reduced volatility at the most critical juncture.
Building a Blueprint That Accounts for Timing
At The Stock Market Blueprint, the core principle is that wealth is not built by accident—it is constructed deliberately, with an understanding of the risks that can quietly undermine even well-executed plans. Sequence of returns risk is precisely the kind of structural threat that rarely appears on a spreadsheet until it is too late.
Investors who plan exclusively around average expected returns are building on an incomplete foundation. A comprehensive retirement strategy must account not just for how much the market returns over time, but for when those returns arrive. The distinction, as history repeatedly demonstrates, can represent the difference between a secure retirement and one defined by difficult trade-offs.
The blueprint for financial independence requires more than selecting the right assets. It demands a clear-eyed understanding of how those assets will behave during the years when your financial future is most vulnerable—and a disciplined plan to protect against the scenarios that average assumptions tend to ignore.